When you take out a logbook loan, your vehicle acts as security. That is why the lender looks closely at the vehicle itself, not only at your income and credit history. Knowing the requirements in advance can save time and help you judge whether this kind of borrowing is realistic for you.
Below, V5 Solutions answers the questions we hear most often about which vehicles qualify.
Which Vehicle Types Can Be Used?
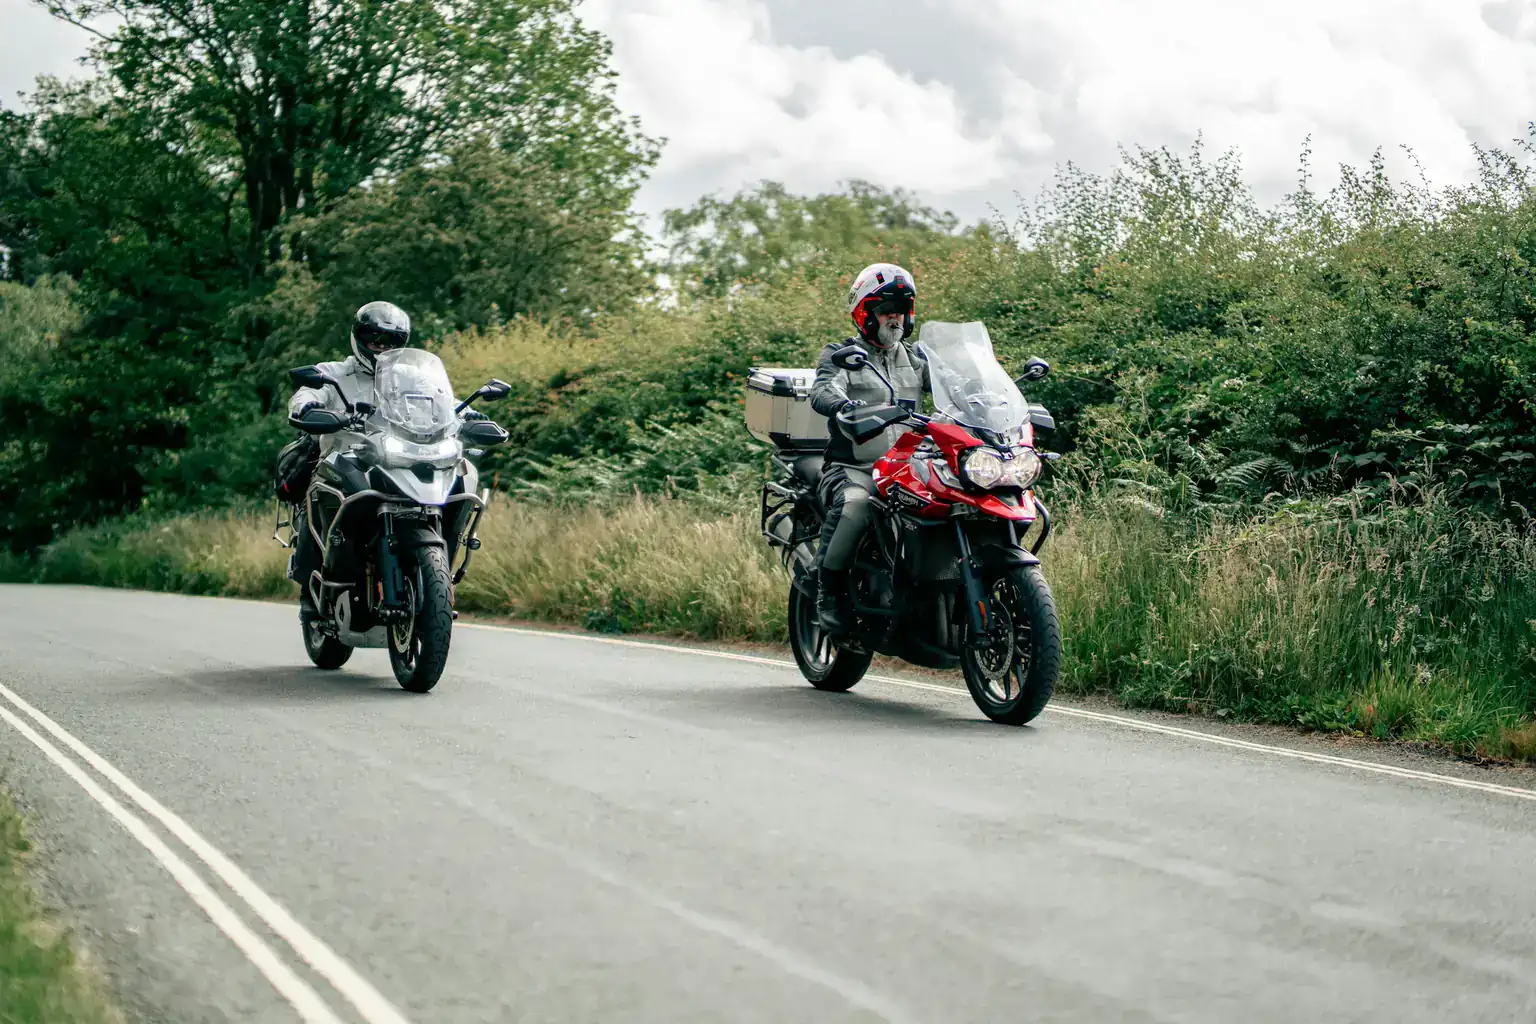
V5 Solutions lends against cars, vans and motorbikes. The same vehicle checks apply to each type. Whether you drive a family hatchback, run a van for work or ride a motorbike, the questions below apply in the same way.
Is There an Age Limit?
There is no single cut-off date. A car that is less than 15 years old has a better chance of acceptance, although make and model play a part too, because some vehicles hold their value much better than others.
Condition is assessed alongside age. The vehicle needs to be in good mechanical and cosmetic order and must have valid road tax, a current MOT and insurance.
Mileage plays a part too. When you ask for a quote, you give us your registration and approximate mileage. After some initial checks, we tell you whether the vehicle looks suitable and the most we could lend, subject to further vehicle, credit and affordability checks. If you want to confirm the tax and MOT status yourself first, the free DVLA vehicle enquiry service on GOV.UK shows both.
Can I Use a Vehicle That Still Has Finance on It?
No. The vehicle must be completely free of outstanding finance. While a hire purchase or PCP deal is running, the vehicle legally belongs to the finance provider until the last payment, so the vehicle is not yours to offer as security. If you have recently cleared a finance agreement, make sure the lender has confirmed it is settled.
If you are weighing up whether to keep paying for a car on finance or buy one outright, our article on the cost of owning your car outright compares the options.
Does the Logbook Need to Be in My Name?
Ideally the V5C shows you as the registered keeper. If it does not, you can still apply as long as you can prove the vehicle belongs to you. The V5C records the registered keeper, who is not always the legal owner, so we may ask for proof of ownership if the two differ.
We never keep your V5C or ask for your spare key. You continue to drive the vehicle throughout the loan.
How Does the Vehicle's Value Affect My Loan?
You can borrow between £1,000 and £50,000, and up to 80% of the vehicle's value. The valuation sets a ceiling, but it does not decide the amount on its own. We check affordability too, using your bank statements and a call with an underwriter, so the offer reflects what you can realistically repay as well as what the vehicle is worth.
For a detailed explanation, see our guide to loan to value on logbook loans.
What Happens to the Vehicle During the Loan?
Your signature on a Bill of Sale passes ownership to V5 Solutions as security until the loan is repaid. For most loans, a signing agent visits to witness the signature and photograph you with the vehicle. In Scotland, and for some other UK loans, the agreement is a Hire Purchase agreement signed online instead.
Repayments are weekly or monthly by recurring debit card payment over 18 to 60 months, and you can settle early at any time with a rebate on interest. When the loan is fully repaid, ownership returns to you. Our step-by-step explanation of what a logbook loan is and our page on how logbook loans work cover the process in more depth.
Secured borrowing is costly, and the consequences of falling behind are serious when you rely on your vehicle every day. Consider alternatives first. This article is general information, not financial advice; if you are worried about existing debts, contact Citizens Advice or National Debtline for free, impartial help.
Your car may be repossessed if you do not keep up repayments on a loan secured against it.